Showing posts with label Eicher. Show all posts

Monday, February 6, 2017

Royal Enfield Jan'17 Sales - Slowest Growth in many years.

Exactly a month ago I had written a report on Royal Enfield's Recent Sales Performance. In that I had specifically mentioned about my expectations for coming months. I am happy to say that Royal Enfield has not managed to perform beyond my expectations, atleast in
January'17. The Total Sales number for Royal Enfield motorcycles during January'17 was 59,676 units, which is 25.1% higher than the 47,710 units number reported for January'16. This is the slowest Y-o-Y growth reported by Royal Enfield in the last many years and are clear signs of the fact that the High-Base effect is finally catching up with this manufacturer of the famous 'Bullet' motorcycles.

Eicher Motors had reported a strong surge in sales of Royal Enfield motorcycles during the 3 months of January to March'16, compared to previous few months, which is now creating a High-Comparison-Base for the company during the corresponding period this year. Hence, despite selling the highest number of motorcycles in a single month in the company's history during January'17, it's Y-o-Y Growth has dropped sharply to 25% from the 42% growth reported in the previous month of December'16. For the next 2 months, I am expecting Royal Enfield to continue despatching increased number of motorcycles, most probably in the range of 60,000 to 62,000 units each month. But the Y-o-Y Growth number will continue to dip further lower to something around 22%. Another interesting factor is that the Low-Base effect for Export Growth comparison ended in January'17 as Royal Enfield had reported sharp increase in Export despatches from February'16 onwards. Hence it will be interesting to see the kind of growth numbers Royal Enfield is able to report for Export sales too going forward.

With monthly sales number of around 60,000 units, Royal Enfield is now competing with the likes of Yamaha India and Suzuki India's 2-wheeler unit in Volume stakes, but it's turnover is way ahead as the Average Selling Price of each unit of Royal Enfield motorcycles is nearly 2 times that of the two Japanese manufacturers. Thanks to the cult-bike image that it's products carry, Royal Enfield is able to price them at a premium and hence the company is able to enjoy way superior EBITDA and Net Profit margins compared to any other 2-wheeler manufacturer in India. It will be interesting to see if this situation remains unchanged even a couple of years down the line or not.

Friday, January 6, 2017

Eicher Motors Ltd. - Royal Enfield's recent Sales Performance & Expectations

In my previous Sales Performance update of Royal Enfield motorcycles, written about 6 months ago, we had seen the monthly sales number to be steady around the 50,000 units mark. With the company commissioning expanded production capacity from the month of July'16, Royal Enfield's monthly sales were expected to go well beyond the 50,000 units mark. Let's check out how the monthly numbers have progressed from the following chart:
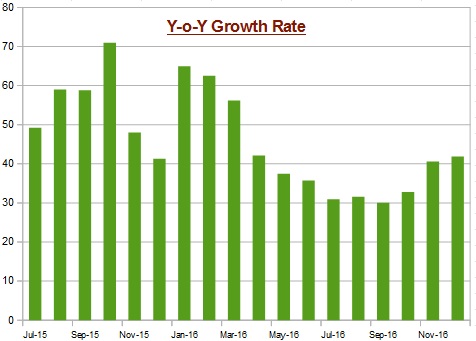
We can clearly see from the chart alongside that Royal Enfield's motorcycle sales consistently improved M-o-M from June'16 till the festival season in October'16, when the monthly number peaked at little over 59,000 units. The figures for November & December'16 have been slightly lower than the peak number, but not as sharply lower as the drop experienced during the last 2 months of Calendar year 2015, when the sales were lower by about 9% compared to the October'15 number. In comparison the monthly sales number for November'16 & December'16 were lower by just about 3% when compared to October'16 number. This is despite the Demonetisation effect that India experienced during the last 2 months. This certainly talks volumes about the demand for Royal Enfield motorcycles. The strong sales performance of Royal Enfield during last 2 months of 2016 compared to last 2 months of 2015 has helped push up the Y-o-Y Growth Rates for the company during the last 2 months, which is seen in the chart below.

Royal Enfield had seen it's Y-o-Y Sales Growth taper off sharply from about 65% level in January'16 to about 30% level for the months of July to September'16. The Y-o-Y Growth Percentage has jumped sharply to over 40% level for the last 2 months, purely because of Low-base effect. Now here comes the challenging part for Eicher Motors & Royal Enfield. Look at the Sales Chart above once again. After low sales numbers for months of November & December'15, the company had seen a sharp jump in sales for the next three months. To be able to report a 40% Y-o-Y growth, Royal Enfield will have to sell in excess of 67,000 units during January'17, which looks quite impossible given the Capacity constraints as well as increased competition, especially from Bajaj's Dominar as well as Yamaha's expected new launch in the higher capacity segment. Even for a 30% Y-o-Y growth, Royal Enfield will have to sell in excess of 62,000 units, which is achievable but won't be easy. My estimate is that Royal Enfield will report sharp drop in Y-o-Y Growth rate for the months of January to March'17, something in the range of 22 to 25%, with monthly sales of around 60,000 to 62,000 units at best. This could be the slowest growth rate posted by Royal Enfield in quite some time. But remember that with increasing comparison base, even growth rate of over 20% is very respectable.

We should also be prepared to see the Y-o-Y Growth rate (possibly) dipping to under 20% during the second half of 2017. In comparison to most other volume bike makers, this growth being experienced by Royal Enfield is still very very respectable. What concerns me is the high expectations that many retail shareholders have from the Eicher Motors' stock. At the current share price of about Rs.22,700/-, Eicher Motors' stock is already trading at over 40 times it's EPS for the Trailing Twelve Months. The company's T-T-M Net Profit has grown at over 60% by September'16. The number for December'16 quarter is also expected to be strong. But I am expecting a deceleration in Net Profit growth for Eicher Motors Ltd from the March'17 quarter to something like 30%, as most of the Profit growth is riding on the back of strong growth in sales of Royal Enfield motorcycles. Hence we should not expect any run-away rally in Eicher Motors' stock going forward. I am expecting the P/E Ratio enjoyed by this stock to gradually come down to 30 to 35 levels over the next 12 months or so. Hence the shareholders of this company should have only moderate returns expectations over the coming months & years. As per my estimate, Eicher Motors will trade in the range of Rs.21,000 to Rs.26,000 over the next 12-15 months.

Friday, July 1, 2016

Eicher Motors Ltd. - Royal Enfield's recent Sales Growth update.

Before you read this post, I would request you to check out my report on this company posted couple of months ago. Here is the link to that report:


Sales of Royal Enfield bikes has remained restricted to a monthly figure of around 50,000 units for the last few months now. Possibly primarily due to capacity limitations. The chart above shows the 3-months moving average of Royal Enfield's monthly sales numbers. We can see the sales plateauing just under the 50,000 units mark for the last 4 months. Once the expanded capacity comes on stream, we will see the sales average breaching past that 50,000 barrier.

One thing that I had mentioned in my report two months ago was that I am expecting Growth rate of Domestic sales to come down substantially from over 50% levels to something closer to 30% by the end of the year. At the same time I was expecting the company to push more volumes into the Export market. Export sales forms just about 2-3% of the company's monthly numbers currently. But the same could be touching 5% by the end of this year and be around 10% by end of 2018. For this to happen, the Export sales should grow at a much faster pace than the company's Domestic sales. I am happy so say that things have already started moving in the direction I had expected. Have a look at the chart below, which shows the progress of Y-o-Y Growth rates of both Domestic & Export sales, again on a 3-months moving average basis.


As we can see, the Y-o-Y Growth rate of Royal Enfield's Domestic sales has sharply come down from 60+% level in March'16 to less than 40% level in June'16. At the same time the Export sales growth rate has improved from about 45% in March'16 to over 80% in June'16. Going forward I am expecting this trend to continue with Export growth to be far higher than Domestic Growth. Since Domestic Sales currently forms about 97% of Royal Enfield's sales, any slowdown in it's growth rate will bring down the over growth rate of the company's Total sales. As I had mentioned in my previous report, even a growth rate of 25 to 30% on such a large base is still very very respectable.

Thursday, June 4, 2015

Eicher Motors Ltd. - Volvo exits it's investment completely.

Exactly three months ago I had written a report on 'over-valuation' of Eicher Motors Ltd. (Click here for that report). In that report I had mentioned Volvo selling more than half of it's holding in Eicher Ltd at a price of little over Rs.15,000/- per share.
During this 3 months period, Eicher Motors stock corrected a bit from levels of over Rs.16,000 to about Rs.14,000/-. But the stock again rallied some more post announcement of March'15 quarterly results to hit a new high of little over Rs.19,000/-. This rally seems to have prompted Volvo to sell the remainder of it's holding too. The sale of the remaining 10 lakh shares, constituting about 3.7% of Eicher Motors' equity was done today morning at a price between Rs.17200 & Rs.18200/-, at a discount to yesterday's closing price. Remember at this price, Eicher Motors' stock trades at about 70 times it's EPS, which ( I would like to repeat ) is very very high valuation for a manufacturing company. I think at the current price Eicher Motors stock is already pricing in growth for the next 2 years atleast, if not more.

According to me, Volvo has done the smart thing of booking all it's profit at current valuations. It's 7-8 years old investment has yielded returns of about 25 to 28 times it's investment. And even after this sale of holding, Volvo's JV with Eicher for manufacture of HCVs stays un-impacted. Since the JV is doing absolutely fine on the business front, I am not expecting Volvo to pull out of it anytime in the near future. But Volvo selling it's over 8% holding in Eicher Motors Ltd in two tranches within a space of just about 3 months is ample hint to other investors. Firstly this deal certifies that the stock is clearly over-valued, because Volvo's JV with Eicher too was part of the the Consolidated entity of Eicher Motors Ltd. Secondly, the floating stock of Eicher Motors Ltd has suddenly increased by nearly 22 lakh shares in the last 3 months.

( Click here for Eicher Motors' Easy Results Summary page. )


Wednesday, March 4, 2015

Eicher Motors Ltd - Royal (Enfield) Ride to Super-High Valuations!!!

The stock of Eicher Motors Ltd has been on an unending upswing for about 6 years now. From levels of about Rs.200-odd in March'2009, the stock rallied to Rs.2500+ levels in March'2013 and further to Rs.15000+ levels in March'2015, i.e. now. The Eicher Motors stock has multiplied over 75 times in the last 6 years and about 5-6 times in just the last 2 years, despite having multiplied over 12 times in the previous 4 years!!!


If we look at Eicher's progress on the business front, the company's Total Income has gone up from Rs.3044 crores in FY'2009 to Rs.8846 crores in FY'2014, i.e. tripling in 5 years time. During the same period Eicher's Net Profit has multiplied seven & half times from Rs.83 crores to Rs.615 crores. This healthy growth in Eicher's business performance & the humongous rise in the company's Market Cap can be attributed to Two major developments in the company's business profile. Sometime during the year 2008, Eicher Motors entered a JV agreement with the Swedish Bus & Truck maker Volvo to jointly manufacture & market Commercial Vehicles. This was the single biggest reason for the start of the rally in Eicher's stock price from Rs.200+ levels in early 2009. This JV with Volvo propelled Eicher's Consolidated Total Income to more than double between FY'2009 to FY'2012, while Net Profit Quadrupled during the same period.

While this JV was powering Eicher's business growth, the company's MD, Siddhartha Lal was working on modernising Eicher's cult bike brand Royal Enfield. During these years the MD invested in R&D for Royal Enfield to make the bikes more reliable, modern, slightly more efficient, all this without compromising on the THUMPing factor behind sales of Bullet range of bikes. All these investments started paying off with increased demand for Royal Enfield bikes, which led to Eicher investing substantial capital to triple the subsidiary's bike manufacturing capacity during FY'2012 & FY'2013. From an annual capacity of about 1.5 lakh bikes, the company expanded it's capacity to nearly 5 lakh bikes. As the expanded capacity started coming on stream, the company started increasing the reach of it's Sales & Service outlets across the country. At the same time the company was reaching out to Foreign markets to ensure that there is healthy demand for it's bikes in the Export markets.

Trailing-Twelve-Months figures


All these efforts are showing terrific results with Royal Enfield's sales growing from monthly numbers of about 10-12,000 units in FY'2012 to about 25,000 units by the end of year 2014. The company sold close to 27,000 bikes in February'2015, again reporting close to 50% Y-o-Y growth, as the company continues to ramp up production at it's plants in a measured fashion. In short, Royal Enfield has been the primary reason of growth for Eicher Motors since FY'2013. The above charts are ample evidence of the same. As can be seen, Eicher's T-T-M Total Income growth, as well as the company's profitability, has picked up pace over the recent 4-6 quarters. For FY'2014, which ended recently, Eicher reported a growth of 28% in Total Income & a growth of 56% in Net Profit, with a very healthy expansion in Net Profit margin in the last year or so. Eicher's EPS for the year ended December'2014 stood at Rs.227/-, while the Cash-EPS stood at Rs.308/-.

Coming to the Valuations part, the Eicher stock trades at very very very Rich valuations. At the current share price of close to Rs.16,000/-, the stock trades at 70 times it's current EPS and 52 times it's current Cash-EPS, which is very expensive according to me. Remember that Eicher Motors Ltd is after all an Automobile manufacturer. These kind of valuations are generally attributed to companies in something like e-commerce space or other service industries where the companies can be expected to easily sustain high growth rates for the next 3-5 years. But an Automobile manufacturer cannot be expected to continue posting 50+% growth rates in Net Profit for many years at a stretch. Royal Enfield is currently growing at a strong pace of about 50%, but the base was small until a year ago. As the base grows larger, the incremental growth rates will taper down to more moderate levels of about 30% over the next 2 years and could go lower after that. One other factor is that cult bikes do sell because of Novelty factor as well as uniqueness factor. With more & more showrooms opening in several cities & towns, the company is selling more & more bikes. The Uniqueness factor will eventually wean away. Royal Enfield can continue to grow for many more years for sure, but I am not expecting the high growth rates to last for anything more than 2-4 years.

Another factor is yesterday's news of Volvo booking profit by selling over 4.50% stake in Eicher Motors Ltd in the open market. Volvo had acquired about 8.40% stake in the company during the JV agreement signing in the year 2008-09. Volvo had paid something like Rs.691 per share that time. That means Volvo made a cool profit of about Rs.14,500 to 15,000 per share on the stake sold, over 20 times it's acquisition price. I think retail investors too should think of selling atleast half of their stake or 3/4th of their holding at current levels. These crazy valuations might not last very long. I could be proven wrong, but I would still be a seller in Eicher Motors Ltd., if I had any shares.